


Net payment terms set how many days a business buyer has to pay an invoice after the invoice date. Under net 30 payment terms, payment is due 30 days after the invoice date; under net 60, 60 days. In B2B commerce, offering net terms helps a seller win trade customers and strengthen business relationships, while the seller carries the wait for its money.
This article is for owners, finance leads and operations heads at distributors, wholesalers and manufacturers who take orders through sales reps, a webstore and marketplaces, with an ERP or accounting system running the books. It covers how net terms work, what payment terms in B2B ecommerce do to cash flow, and how to sell on credit online while keeping control of who buys on account and how much.
The decision about extending credit to a customer, and how much, belongs to your business and its finance team. This article explains the mechanics. It does not give credit, legal or tax advice.
What are net payment terms?
Net payment terms are a standard method in business to business transactions. They set the amount of time a buyer has to pay an invoice after receiving goods or services, usually stated as net 15, net 30, net 60 or net 90, depending on the agreement between buyer and seller.
For example, under net 30 payment terms a business must pay the invoice within 30 days of the invoice date. The buyer gets a payment period to receive the goods or services, check them and often sell some of them before the money leaves its account.
Common net terms and their due dates
The number after “net” is the number of days from the invoice date to the due date. The table uses a hypothetical invoice dated 1 March.
| Term | Payment is due | Due date for an invoice dated 1 March |
|---|---|---|
| Net 15 | 15 days after the invoice date | 16 March |
| Net 30 | 30 days after the invoice date | 31 March |
| Net 45 | 45 days after the invoice date | 15 April |
| Net 60 | 60 days after the invoice date | 30 April |
| Net 90 | 90 days after the invoice date | 30 May |
Net 30 payment terms are the ones most buyers recognise. Longer payment terms such as net 60 and net 90 tend to follow longer project or resale cycles, and they depend on industry norms and on the contract.
Early payment discounts such as 2/10 net 30
“2/10 net 30” means the buyer may take a 2% discount if it pays within 10 days; otherwise the full payment is due in 30 days. For example, on a hypothetical invoice of USD 10,000, the buyer pays USD 9,800 by day 10 or USD 10,000 by day 30.
Early payment discounts encourage customers to pay sooner and give the seller its cash earlier, at the cost of the discount.
Other payment terms you will see
- Due on receipt: the buyer must pay immediately when the invoice arrives.
- End of month (EOM): the count starts at the end of the invoice month, so “net 30 EOM” on a 10 March invoice is due 30 April.
- Advance payment: the buyer pays before the goods ship, common for new accounts.
- Partial payments: a deposit now and the balance on terms, or installment payments on a schedule.
Net terms, trade credit and DPO
Net terms are a form of trade credit: the seller lets the buyer take goods or services now and pay later, usually without interest if the buyer pays on time. On the buyer’s side, longer payment terms raise its days payable outstanding (DPO), the average number of days its accounts payable stay open, and hold cash in its business longer.
On the seller’s side, the same invoices sit in accounts receivable until they are paid. One invoice’s accounts payable is another company’s accounts receivable, which is why payment terms are negotiated so carefully.
Why B2B sellers offer net payment terms
Buyers expect them. For example, Amazon Business says it has renamed Pay by Invoice to Business Credit Account, an invite-only option for eligible business customers with 30-day payment terms and no upfront fees, as listed on 10 November 2026.
Strengthening customer relationships
Offering net terms accommodates a customer’s financial needs and can strengthen customer relationships. Whether it is net 30 or net 60, removing the need to pay upfront makes buying easier, which supports customer loyalty and repeat business. Customers who value the flexibility are more likely to come back.
Easier buying and larger orders
Payment terms let buyers order what they need now and pay from the revenue the goods bring in. Small businesses in particular can place a larger order on net 30 payment terms than they could fund upfront, and they can reorder before the last invoice is paid.
Gaining a competitive advantage
Flexible payment terms can be a competitive advantage. Accommodating customers’ financial schedules may attract customers who find upfront payment or short terms elsewhere hard to manage.
The risks and cash flow effect of net terms
Net terms have costs, and the risk of late payment rises when nobody checks a credit limit before an approved buyer orders again. Sellers should plan for these drawbacks:
- Late payments: customers miss the payment deadline, which disrupts the company’s cash flow and adds collection work and, where agreed, late fees.
- An interest-free loan: a longer payment period such as net 60 or net 90 acts like an interest-free loan to the customer, which can strain the seller’s cash flow.
- The company’s cash flow requirements: it is hard to balance cash flow against the costs of business operations, particularly when longer terms are given in exchange for higher-volume orders.
- Bad debt: some invoices are never paid in full, and the loss falls on the seller.
How net 30 and net 60 affect cash flow
For example, with hypothetical numbers: a distributor invoices USD 100,000 a month and every customer pays exactly on the due date, the most predictable cash flow possible. On net 30, about one month of sales, USD 100,000, is always waiting in receivables. On net 60, about USD 200,000 is waiting.
The extra USD 100,000 has to come from somewhere: the owner’s cash, a bank facility or slower payments to the distributor’s own suppliers. For small businesses with thin reserves, that gap is the main cost of moving customers from net 30 to net 60, before any late payments.
Who gets net payment terms, and where the credit limit lives
Most businesses offer net terms only to approved accounts in their customer base. A buyer applies, the finance team reviews its financial stability, and the account is set up with B2B credit terms: a payment term and a credit limit. Those decisions belong to the business; what follows is how the systems should carry them out.
Credit limits in the ERP or in the store
The credit limit should live where the open invoices live, usually the ERP or accounting system. That is the only place that knows what the customer owes today.
The webstore then needs available credit: the limit, minus open invoices, minus orders placed but not yet invoiced. If the store reads only the limit, a buyer can place several orders in a day that together go far over it.
Orders that go over the credit limit
Decide in advance what happens when an order would take the account over its limit. The common choices are to hold the order for finance approval, to ask for part of the order to be paid by card or bank transfer, or to block it.
Whichever you choose, tell the buyer at checkout and record who released a held order and why. A held order that nobody sees is a lost order.
Holding orders when invoices are overdue
Many sellers put an account on hold when an invoice remains unpaid more than an agreed number of days after it is due, and apply any late fees the agreed payment terms allow. The store should show the buyer why, which overdue invoices to pay and how, and release the hold automatically once payment is recorded in the ledger.
Making invoices and due dates agree with the books
The due date is calculated from the invoice date, so the payment timeline must be the same in the store, on the invoice and in the accounting ledger. In the invoicing process, problems start when the store counts from the order date and the accounting system counts from the shipping date.
Partial shipments make this harder. Each shipment may create its own invoice with its own payment timeline, and the buyer’s portal should list them the same way the ledger does.
The order should also keep the payment terms that applied when it was placed. If a customer moves from net 30 to net 60 next month, invoices for earlier orders keep their original due dates.
Accounting systems handle the defaults. For example, Xero describes setting a default invoice due date for the organisation and a different due date for a specific customer, which overrides the default, as listed on 10 November 2026. The store should read those payment terms from the accounting system, not keep its own copy.
Sales reps ordering on behalf of customers
Sales reps often place orders for their accounts by phone, by email or in the portal. Those orders should pass the same credit check, use the same payment terms and land on the same ledger as orders the buyer places online.
The order should record who placed it. If reps can override a hold or a term, that override needs the same approval and record as any other exception, or reps and finance will give the buyer different answers.
Early payment discounts and late fees
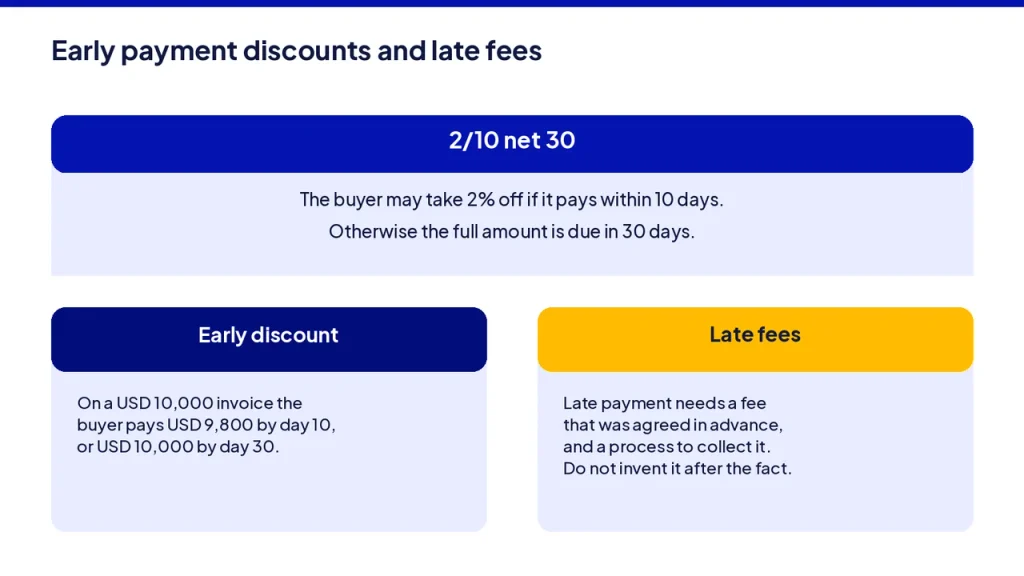
Offering optional early payment discounts gives customers a reason to pay sooner than the net term requires. A 2% discount for early payment can help keep a healthy cash flow and reduce late payments, but it is a real cost, so the business should know what earlier cash is worth to it.
Early payment discounts must appear on the invoice and in the ledger the same way: the invoice shows both amounts and both dates, and the accounting system records the discount only when payment arrives inside the window.
Late fees work the other way. Late payment fees, interest on overdue balances and the right to stop supply must be written into the agreed payment terms before the first order, and they are subject to local rules, so check them with your own advisers.
Managing net terms day to day
To make net payment terms work for both the business and its customers, a few routines matter more than any single tool.
Monitor payment history
Regularly assess each customer’s payment history and adjust payment terms when the pattern changes. Reliable customers with a record of financial reliability may earn longer terms; if a customer often pays late, the business may decide on shorter payment terms, a lower limit or stricter payment schedules to encourage timely payments.
Automate invoicing and payment reminders
Billing and payment systems that send invoices on time and send payment reminders as the payment deadline approaches reduce human error and save time. Automated payment reminders before and after payment is due help manage accounts receivable and identify overdue invoices early, and they improve customer relationships compared with chasing by phone. Weigh the transaction costs of any payment tool against the time it saves.
Set terms by customer, not by habit
Set payment terms based on each customer’s needs and record. For example, high-volume buyers may receive net 60 with pricing tied to account value and risk, while smaller businesses receive net 30 payment terms. Different terms for different customer groups need clear approval rules so that pricing and terms stay consistent across reps and the webstore.
Review payment terms regularly
Review payment terms regularly against the average collection period, overdue balances, early payment discounts taken and cash flow needs. Whatever the right tech stack looks like for your business, the review only works if the store, the ERP and the accounting system report the same payment data.
Financing options when terms strain cash flow
When net terms run ahead of cash flow needs, businesses use several financing options. Invoice factoring means selling unpaid invoices to a third party for immediate cash, less a fee. Invoice financing uses unpaid invoices as security for a loan. Some sellers use trade credit insurance to cover customers who do not pay.
Each option has a cost and its own contract terms. Which one fits, if any, is a decision for the business and its financial advisers.
Frequently asked questions about net payment terms
What are net payment terms in B2B transactions?
Net payment terms are agreements between businesses that set how long a customer has to pay an invoice after the customer receives goods or services. For example, “net 30” means the customer must pay within 30 days of the invoice date.
What are the most common net payment terms?
The most common are net 15, net 30, net 45, net 60 and net 90, with net 30 payment terms the most widely recognised. The number is the days from the invoice date until payment is due. Some sellers add early payment discounts such as 2/10 net 30.
What is the difference between net 30 and net 60?
Net 30 requires payment within 30 days of the invoice date, while net 60 gives the customer 60 days. Net 60 is an extended payment term: it gives the buyer more time and leaves the seller waiting twice as long to receive payment.
How do net 30 and net 60 payment terms affect cash flow for small businesses?
For a small business selling on terms, longer terms mean more cash waiting in receivables: on net 60, roughly twice as much as on net 30 for the same sales. For a small business buying on terms, net 30 or net 60 allows purchases on credit and more time to sell the goods before paying the supplier.
What is a prompt payment discount?
A prompt payment discount is one of the early payment discounts: an incentive for paying early. For example, a supplier might offer 2% off if the invoice is paid within 10 days, which speeds up payment and improves the supplier’s cash flow.
How does the average period collection formula work?
The average collection period is accounts receivable divided by total credit sales for the period, multiplied by the number of days in the period. It shows how long customers actually take to pay, which tells you whether your payment terms are being kept.
Can businesses use invoice factoring to manage cash flow on net terms?
Businesses can sell unpaid invoices to a factoring company for immediate cash, less a fee. It can ease cash flow gaps caused by delayed payments, at a cost the business should weigh against other financing.
Are net payment terms different for different industries?
Net payment terms vary by industry norms, contract size and the length of the buyer’s own sales cycle. Industries with long projects or slow resale tend to see longer payment windows, while fast-moving goods, such as in the food and beverage industry, often run on shorter ones.
How does the “pay by invoice” model work?
Pay by invoice lets an approved business buy goods or services and pay invoices later, typically within 30, 60 or 90 days. It is common with larger buyers and wholesale customers who order through customer portals.
What is a standard payment term?
A standard payment term is the default time a business gives customers to pay, such as net 30. It applies unless a customer has agreed different terms, and it usually ranges from net 15 to net 90 depending on industry standards and business needs.
Net terms, orders and the ledger on one system
A Malaysian paint manufacturer has run its orders and stock on a system KVY built and has operated since January 2025. Its sales orders sync to QNE Cloud accounting with Malaysian e-invoice fields, and order lines keep a snapshot of price, unit and tax at the moment of sale, so the invoice matches the order the buyer placed.
That is the work KVY TECH does in B2B ecommerce development: a wholesale ecommerce platform where terms, credit limits and invoices come from the same books as the rest of the business.
If you are weighing this for your own business, start with a plan. In two to three weeks we map how the system would connect to your ERP, warehouse, payments and sales channels, set out the build in phases with the cost to run it over three years, and give a fixed quote for the first phase. You keep the plan whatever you decide.